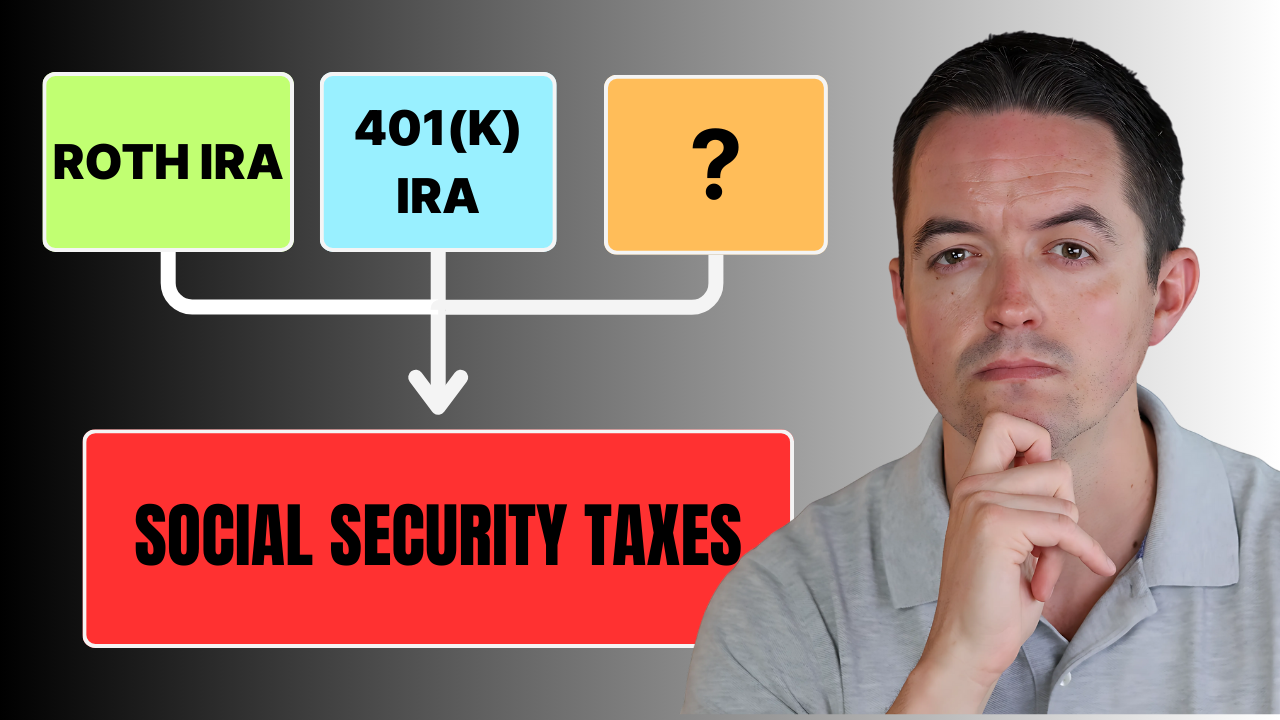
The Social Security "Tax Torpedo" is a phenomenon that surprises many retirees. It occurs when additional income leads to a higher portion of Social Security benefits being taxed, effectively increasing the overall tax rate. Here's an in-depth look at how it works and strategies to avoid it.
In the U.S., we have a progressive tax system for ordinary income, meaning that different portions of your income are taxed at different rates. For example, if you have taxable income of $70,000, your income is taxed as follows:

Your marginal tax rate determines the tax on your next dollar of income, which is critical for planning withdrawals in retirement.
Social Security benefits are taxed based on provisional income, which is calculated as:
Based on provisional income, a portion of your Social Security benefits will be taxable:

Let’s consider a retiree with the following income sources:
The provisional income is calculated as:
Since this exceeds $34,000, 85% of Social Security benefits become taxable.
Suppose this retiree needs an extra $1,000 for an emergency expense. They withdraw it from their IRA, assuming it will be taxed at their 22% marginal rate ($220). However, this withdrawal increases their taxable income by $1,850, including $850 more of their Social Security benefits. The actual tax bill increases by $407, creating an effective tax rate of 40.7% on the additional withdrawal.
The Tax Torpedo happens because additional income causes more of your Social Security benefits to be taxed. Once 85% of your benefits are taxable, further income is taxed only at your marginal rate, but reaching that point can result in unexpectedly high taxes.
Converting funds from a traditional IRA or 401(k) to a Roth IRA early in retirement can help. Since Roth withdrawals are tax-free, they won’t increase your provisional income. This strategy is especially effective before claiming Social Security benefits.
Investing in a taxable brokerage account creates a source of funds subject to capital gains tax rather than ordinary income tax. This diversifies your income sources and reduces the impact on provisional income.
Delaying Social Security benefits until age 70 increases your monthly payments and allows you to spend down pre-tax accounts earlier. This reduces Required Minimum Distributions (RMDs) later, which can otherwise push you into higher tax brackets.
Work with a financial advisor to determine the optimal sequence for withdrawals. Combining withdrawals from taxable, tax-deferred, and tax-free accounts can help you stay within lower tax brackets.
Navigating taxes in retirement requires careful planning. By understanding the Tax Torpedo and employing these strategies, you can keep more of your hard-earned money. For more insights, subscribe to our channel or consult a certified financial planner.
If you found this information helpful, subscribe to our YouTube channel to stay updated. Schedule an intro call to see if we're a good fit to work together!