For years, a common rule of thumb has been that you need $1 million to retire comfortably. But with inflation and rising costs, many people are now targeting $2 million or more. That was the case for Sarah and Ian — a couple in their late 50s and early 60s — until a detailed retirement plan revealed they could retire on far less, without sacrificing the lifestyle they wanted.
In this post, we’ll walk through their real-life case study and how smart retirement planning and tax strategies gave them the freedom to retire earlier, with confidence.
Watch on YouTube:
Sarah (58) and Ian (60) had saved $1.4 million for retirement:
They also had no debt and expected to receive Social Security benefits of $2,800/month (Sarah) and $3,100/month (Ian) starting at full retirement age (67). Their goal was to retire at age 65, coinciding with Medicare eligibility.
Their desired retirement lifestyle included:
Sarah and Ian assumed they needed $2 million to safely retire. But their financial plan showed otherwise. With $1.4 million, they had more than enough — especially with strategic tax planning and flexible spending strategies.
Here’s why:
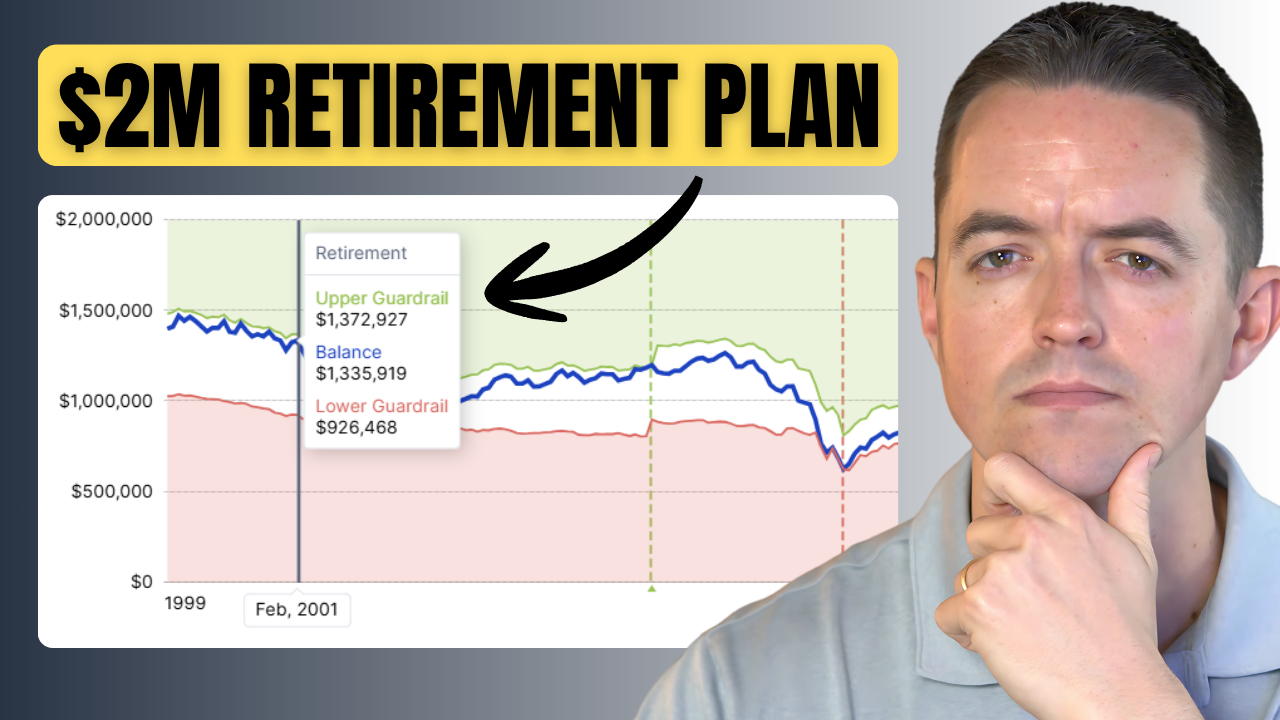
Instead of relying on rigid rules like the 4% rule, Sarah and Ian used a retirement income guardrails strategy. Here’s how it worked:
For example, if their portfolio dropped 30% from $1.6 million to $1.1 million, they'd only need to reduce monthly spending by $500 to remain sustainable — a manageable adjustment.
Sarah and Ian’s plan leveraged their account types in a tax-efficient order:
This withdrawal strategy kept their taxable income low, especially during the early years of retirement before Social Security and Medicare kicked in.
One roadblock to retiring before 65 was healthcare. But thanks to their low taxable income, Sarah and Ian qualified for ACA subsidies, drastically reducing their health insurance premiums.
This unexpected benefit made retiring earlier much more feasible — and further reduced their reliance on the $2 million target.
To protect against market volatility, their new retirement portfolio included:
This allowed them to avoid selling stocks during downturns — a key principle in sustainable retirement planning.
Using historical simulations (e.g., retiring during the dot-com crash and 2008 financial crisis), the plan was stress-tested.
Results showed:
The key takeaway? With a flexible, well-diversified plan, even the worst-case scenarios weren’t catastrophic.
In their baseline plan, both Sarah and Ian claimed benefits at 67. But in scenarios where they retired earlier, they explored claiming as early as 62 to reduce portfolio withdrawals.
Yes, the monthly benefits would be smaller, but the tradeoff was preserving more of their investments — especially valuable during market downturns.
They considered converting funds from their traditional IRA to Roth IRAs to save on long-term taxes. But early on, preserving ACA healthcare subsidies was more valuable than the tax benefit of conversions.
The plan is to revisit Roth conversions after age 65, once they’re on Medicare and income-based subsidies are no longer a factor.
In the end, Sarah and Ian decided on a “happy medium”:
They ended up needing far less than $2 million — and more importantly, they gained the confidence to enjoy the retirement they envisioned without extra years in jobs they didn’t love.
Whether you’re targeting $1 million, $2 million, or another number entirely, this case study shows that retirement isn’t about hitting a magic number. It’s about smart, tax-efficient planning, understanding your spending patterns, and having the flexibility to adapt.
A few key takeaways:
If you’re approaching retirement and unsure whether your current plan will support your goals, we offer a free retirement and tax planning assessment to walk through your situation — just like we did for Sarah and Ian.
[Click here to schedule your free retirement planning session.]
Let’s create a retirement plan that’s built around your life — not just a number.